The primary value of integrating artificial intelligence into biological research is the dramatic reduction in time required to identify viable therapeutic targets. This acceleration represents a seismic shift in how the financial markets value biotechnology, moving it from a speculative sector into a core pillar of tech-driven growth. The urgency behind this transition is often deeply personal, as seen in the narratives of technology leaders who have watched loved ones succumb to diseases that were cured only a few years after their passing. In the current landscape of 2026, the gap between a terminal diagnosis and a life-saving treatment is narrowing at an unprecedented rate, largely due to the infusion of machine learning into the drug discovery pipeline. This realization has catalyzed a massive reallocation of capital from traditional physical sciences into the burgeoning field of computational biology. The overarching objective is no longer merely to manage symptoms or achieve incremental improvements in patient outcomes; instead, the focus has shifted toward the ambitious goal of reversing cellular aging and fundamentally extending the human lifespan. For the modern investor, participating in this sector is increasingly viewed as a pursuit of longevity itself, ensuring that one’s portfolio and health remain robust enough to benefit from the rejuvenation therapies being pioneered by advanced silicon-based intelligence systems.
Identifying the Infrastructure Bottleneck: The Shift to Upstream Assets
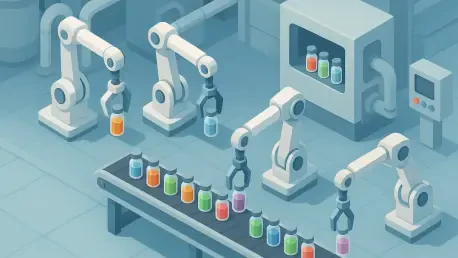
The current investment logic in the pharmaceutical industry has matured significantly, moving away from a high-stakes search for individual blockbuster drugs toward a more sustainable focus on the infrastructure that supports widespread discovery. While the initial excitement surrounding artificial intelligence was centered on its ability to dream up new molecules, the industry quickly encountered a structural imbalance between digital design and physical execution. It is helpful to view this through the lens of a traditional gold rush, where the most consistent profits are rarely found by the miners themselves but by the individuals selling the shovels and pickaxes. In 2026, the miners are the biotech startups attempting to validate a single therapeutic hypothesis, while the shovel sellers are the upstream companies providing the synthesis and testing capabilities necessary for any drug to move from a computer screen into a clinical trial. This shift is necessitated by the fact that AI can now generate thousands of candidate molecules in the time it previously took a human team to hypothesize one, creating a massive backlog in the laboratory pipeline that only industrial-scale automation can resolve.
This structural imbalance between the waitstaff of AI designers and the kitchen of physical laboratories has become the primary constraint on medical progress. In the past, a standard laboratory might have handled a hundred molecular designs in a single day, but modern AI models are currently generating upwards of ten thousand candidate structures in the same timeframe. Without a massive expansion in automated laboratory infrastructure, these digital designs remain purely theoretical and provide no clinical value. Therefore, high-conviction investment opportunities are increasingly found in the companies that provide the essential building blocks of research, such as synthetic DNA, specialized proteins, and high-throughput robotic systems. By focusing on these upstream providers, investors can gain exposure to the entire volume of pharmaceutical innovation rather than betting on the survival of a single molecule. The true bottleneck is no longer the intelligence of the model, but the physical capacity to manufacture and test the designs that the model produces, making the companies that bridge this digital-to-physical gap the most valuable players in the current market cycle.
Strategic Advantages: Upstream Investing and Risk Mitigation
Investing in a specific drug developer remains an inherently binary and high-risk endeavor because the path to regulatory approval is fraught with potential for failure. A company might spend an entire decade and billions of dollars on a single anti-cancer drug, only to have it fail in late-stage clinical trials, leading to a catastrophic loss in equity value. In contrast, the upstream suppliers that facilitate these experiments operate on a volume-based business model that is largely agnostic to the success or failure of any individual drug. These providers do not necessarily care which specific therapeutic candidate reaches the market; they benefit from the sheer increase in the total number of experiments being conducted across the industry. As the integration of AI forces pharmaceutical companies to run more tests, synthesize more genetic material, and analyze more cellular reactions, these infrastructure providers receive a steady and growing stream of orders. This creates a diversified revenue base that is much more resilient to the volatility typically associated with the biotechnology sector.
The emergence of the data closed loop has further solidified the importance of these upstream service providers as essential partners in the R&D process. In this model, an AI generates a hypothesis, a laboratory tests that hypothesis using physical materials, and the resulting data is fed back into the model to refine its next set of predictions. This cycle requires a continuous and recurring purchase of laboratory reagents, synthetic DNA, and automated testing services to maintain the momentum of discovery. For the supplier, this relationship creates a predictable and growing demand for their products, turning them into the essential fuel for the modern pharmaceutical engine. This shift toward a recurring revenue model is particularly attractive to institutional investors who favor stability and scalability over the high-risk gambles of traditional drug development. By supporting the massive experimentation cycles required by machine learning, upstream companies have effectively turned the biological research process into a scalable industrial operation that rewards consistency and technological precision.
The Evolution: Transforming Laboratories into Data Factories
A critical trend currently reshaping the industry is the movement toward Virtual Biology Initiatives and the creation of massive biological data infrastructure projects. High-profile initiatives, such as the Biohub project supported by major technology foundations, have poured billions into the development of high-quality, standardized biological datasets. These projects highlight a fundamental reality of the modern erartificial intelligence models are only as effective as the data used to train them. Currently, the pharmaceutical industry is facing a significant shortage of the repeatable and standardized data points necessary for high-level machine learning. To address this deficiency, the role of the laboratory is evolving from a simple verification center where individual hypotheses are tested into a high-throughput data production plant. These modern factories of biology are designed to subject cells to thousands of different conditions simultaneously, with every reaction recorded as a digital data point to be consumed by training algorithms.
This industrialization of biology ensures that AI systems have the massive datasets required to make accurate predictions about human health and complex disease states. In these high-throughput environments, every movement is tracked, and every cellular change is imaged, creating a digital twin of the biological process that can be analyzed at a scale previously unimaginable. This shift moves the industry away from artisanal science, where experiments were conducted by hand and subject to human error, toward a standardized model of discovery. The companies providing the imaging software, the robotic arms, and the high-sensitivity sensors required to run these data factories are positioned at the center of this transformation. As the pharmaceutical sector continues to prioritize data generation as its most valuable output, the demand for the tools that enable this high-velocity research will only continue to accelerate. This represents a fundamental change in the identity of a pharmaceutical company, as they begin to resemble data processing firms more than traditional chemical manufacturers.
Case Study: Implementing the Design-Test-Learn Loop
Recursion Pharmaceuticals serves as a primary example of how the integration of AI and automated physical biology can revolutionize the discovery process. Through high-level collaborations with global pharmaceutical leaders, the company has demonstrated the power of a fully integrated R&D cycle that minimizes human guesswork. Rather than searching for drug targets based on manual observation, the process utilizes advanced stem cell technology to culture vast quantities of specialized cells, such as neurons, which are then subjected to genetic perturbations. Automated imaging systems capture millions of high-resolution images of these cells, allowing AI models to detect subtle changes that would be invisible to the human eye. This approach effectively turns biological research into a scalable digital process, where the focus is on identifying patterns across massive datasets rather than testing individual theories one by one. The scale of these operations is truly staggering, with some facilities culturing over a trillion cells and capturing tens of millions of images to fuel their discovery engines.
The success of such integrated operations has already led to the discovery and experimental verification of new therapeutic targets in complex fields like neuroscience and oncology. However, even the most self-sufficient and integrated companies must still rely on a massive supply chain of raw materials to maintain their experimentation speed. To culture a trillion cells and perform millions of genetic tests, a company must purchase an enormous volume of synthetic DNA, specialized growth reagents, and high-end laboratory equipment. This reality reinforces the investment thesis that the leaders in the synthesis and testing markets are the primary beneficiaries of the AI revolution. Even as discovery companies become more efficient and successful, their need for the underlying “fuel” of research—provided by upstream specialists—only grows in tandem with their experimental throughput. This case study proves that the design-test-learn loop is no longer a futuristic concept but a functional and highly productive R&D process that is already delivering tangible results in the current market.
Leaders: Navigating the Synthesis and Testing Markets
Twist Bioscience has established itself as a dominant leader in the synthesis market, occupying a critical position at the very beginning of the physical realization phase of drug discovery. When an AI model designs a new protein or a novel therapeutic sequence, that digital information must be translated into a physical DNA strand before it can be tested. By utilizing proprietary silicon-based chips and advanced automation, this company can synthesize DNA at a scale and cost that traditional methods simply cannot match. This technological advantage has translated into significant financial performance, with recent reports showing a 39% increase in revenue for their DNA synthesis and protein solutions business. Even more telling is the massive 56% jump in the delivery of synthesized genes, a metric that directly reflects the increasing volume of AI-generated designs entering the physical testing phase. As researchers continue to demand higher volumes of custom genetic material, the company’s role as the master of synthesis makes it a cornerstone of the modern bio-economy.
On the testing and verification side of the industrial chain, Revvity provides the essential tools required to measure the biological impact of these new materials. Their business model follows a classic razor and blade strategy, where they sell high-end laboratory instruments that then require a continuous supply of proprietary reagents and consumables to operate. As AI increases the volume of candidate molecules, researchers are forced to perform exponentially more tests to check for toxicity, binding affinity, and cellular impact. Each of these millions of tests requires the specialized reagents and software provided by companies like Revvity. This creates a stable and recurring revenue floor that protects the company from the cyclical nature of equipment sales. For investors, this represents a diversified way to play the AI pharmaceutical trend, as the company’s products cover the entire testing lifecycle of a drug. While equipment sales might fluctuate based on capital budgets, the recurring demand for testing supplies ensures that the company remains a primary beneficiary as the total volume of pharmaceutical experimentation scales upward.
Strategic Conclusions: The Future of the Bio-Economy
The comprehensive analysis of the pharmaceutical landscape revealed that the initial period of excitement over computational models transitioned into a deep realization that physical testing infrastructure is the current growth limiter. The shift from dry lab discovery to wet lab verification became the defining characteristic of the market as investors recognized that digital designs have no value without biological validation. It was observed that to make biology truly computable, the industry had to embrace the standardization and automation provided by upstream leaders. This movement effectively eliminated the human error inherent in artisanal science and replaced it with a model of industrial-scale data generation. Because the goals of this sector are tied to fundamental human survival and the extension of the lifespan, the capital expenditure into this infrastructure was sustained at high levels throughout the current cycle. The market successfully re-priced these upstream companies, recognizing their newfound role as the essential backbone of the AI-driven biological revolution.
To capitalize on these developments, investors should prioritize a thorough analysis of the financial reports of infrastructure and tool providers rather than focusing solely on the clinical trial updates of drug developers. One of the most effective next steps is to monitor the growth in recurring reagent sales and the volume of synthetic gene orders, as these metrics serve as leading indicators for the overall health of the AI drug discovery sector. It is also recommended to look for companies that are successfully integrating their hardware with proprietary AI software, creating a moat that is difficult for competitors to breach. As the laboratory environment continues to modernize to meet the demands of machine learning, the strategic focus should remain on those who provide the essential materials for the design-test-learn loop. Ultimately, the most successful participants in this era were those who recognized that in the race to conquer disease and extend human life, the tools used to run the race are just as valuable as the finish line itself. Objective analysis suggests that we are still in the early stages of this long-term growth trajectory, making the present moment an ideal time for strategic positioning in infrastructure assets.